ICE Lines Up $3.7 Billion Notes and $2 Billion Loan for MarketAxess
ICE sold four tranches of senior notes, signed a $2 billion delayed-draw term loan and cut its $6.2 billion bridge to zero to finance the MarketAxess deal.
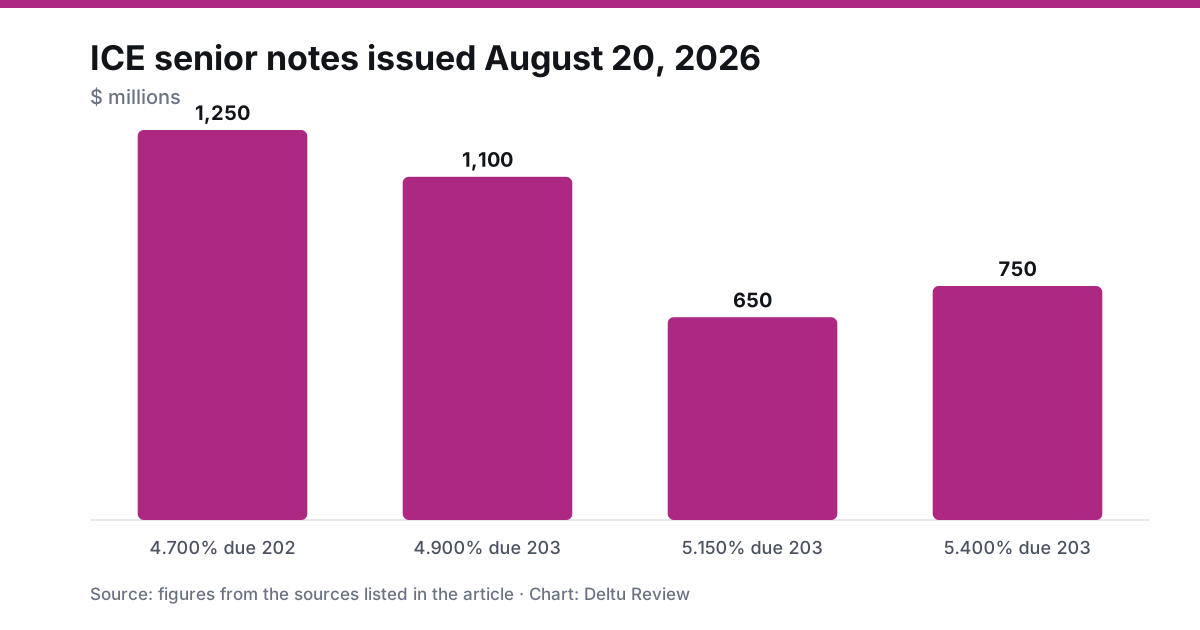
| Component | Amount | Key terms |
|---|---|---|
| 4.700% notes due 2029 | $1,250 million | Senior unsecured |
| 4.900% notes due 2031 | $1,100 million | Senior unsecured |
| 5.150% notes due 2033 | $650 million | Senior unsecured |
| 5.400% notes due 2036 | $750 million | Senior unsecured |
| Delayed-draw term loan | $2.0 billion | Matures 24 months after funding |
| MarketAxess revolver class | $1.5 billion | Within the $3.9 billion revolver |
| Bridge commitment | $6.2 billion to $0 | Cancelled August 20 |
Intercontinental Exchange has finished lining up financing for its acquisition of MarketAxess, according to two 8-K filings on August 20 and 21. The company issued four tranches of senior notes, signed a new term loan and amended its revolver, which allowed it to cancel the $6.2 billion bridge commitment announced with the deal on July 30.
The bond sale
ICE completed the offering of $3.75 billion of senior notes on August 20, after pricing under an underwriting agreement dated August 11. The four maturities run from 2029 to 2036, with coupons from 4.700% to 5.400%. Net proceeds were about $3.71 billion. The notes were sold off ICE’s automatic shelf registration, with BofA Securities, Wells Fargo Securities, MUFG, Citigroup, Fifth Third and PNC acting as representatives of the underwriters. ICE said it will use the proceeds, with the term loan, commercial paper, revolver borrowings and cash, to pay the MarketAxess purchase price and related costs.
Term loan and revolver
The new term loan is a $2.0 billion delayed-draw facility with Bank of America as agent. It has no required amortization and matures 24 months after funding. Borrowings bear interest at Term SOFR plus 0.625% to 1.250%, or a base rate plus 0% to 0.250%, depending on ICE’s ratings, and can be prepaid without penalty.
ICE also signed a Fourteenth Amendment to its credit agreement with Wells Fargo as agent. Lenders holding $3.67 billion of commitments agreed to extend maturity to August 20, 2031, and the amendment creates a $1.5 billion class of “MarketAxess Revolving Commitments” for the acquisition. Total commitments stay at $3.9 billion. The facility has an option to grow by up to $1.25 billion and includes a leverage maintenance covenant.
Why it matters
The permanent cut of the bridge from $6.2 billion to zero means the backstop arranged on July 29 in case incremental debt was unavailable is no longer needed. The financing is also in place before MarketAxess shareholders have voted and before regulators have cleared the deal, which ICE expects to close in the first half of 2027. At its July 30 earnings, ICE reported $19.8 billion of debt outstanding at June 30, so the new borrowing adds materially to a balance sheet that the company has said it will bring back to 3.0 times gross leverage or lower within 18 to 24 months of closing.
Prepared with AI assistance from public sources and reviewed under our editorial policy. Not investment advice.