ICE to Buy MarketAxess for $6.0 Billion in Fixed Income Markets Deal
Intercontinental Exchange agreed to buy MarketAxess for $167 per share in cash, a 33% premium. Fees, closing conditions and financing terms from the 8-K.
| Term | Detail |
|---|---|
| Acquirer / target | Intercontinental Exchange (NYSE: ICE) / MarketAxess Holdings (Nasdaq: MKTX) |
| Price | $167 per share in cash, a 33% premium to the July 29 close |
| Equity value / enterprise value | About $6.0 billion / about $5.7 billion |
| Synergies | $100 million annual run-rate expense synergies within three years |
| Financing | New debt; $6.25 billion bridge commitment from Bank of America as backup |
| Break fees | $148.8 million payable by MarketAxess; $327.4 million regulatory fee payable by ICE |
| Expected close | First half of 2027 |
Intercontinental Exchange said on July 30 that it will acquire MarketAxess, the electronic trading platform for institutional bonds, in an all-cash deal that the companies value at roughly $6.0 billion in equity. The merger agreement is dated July 29, and both boards approved it unanimously. The deal is a bet that fixed income markets, which ICE describes as still largely manual and bilateral, can be moved onto the same kind of networked infrastructure ICE built in energy, credit default swaps and mortgage technology.
Strategic case
MarketAxess connects about 2,100 institutional investors and broker-dealers in more than 90 countries and handles corporate bonds, municipal bonds, emerging market debt, Eurobonds and U.S. Treasuries. ICE brings a retail and wealth bond trading franchise, fixed income pricing and reference data, and a global index business. The companies say the combination will cover pre-trade analytics, execution and post-trade data in one workflow. ICE cites an estimated $145.1 trillion of global bonds outstanding.
ICE expects the deal to be accretive to adjusted earnings per share in the first full year after closing, and puts the enterprise value at about 10.6 times MarketAxess trailing EBITDA, pro forma for the full run-rate synergies.
Financing and capital returns
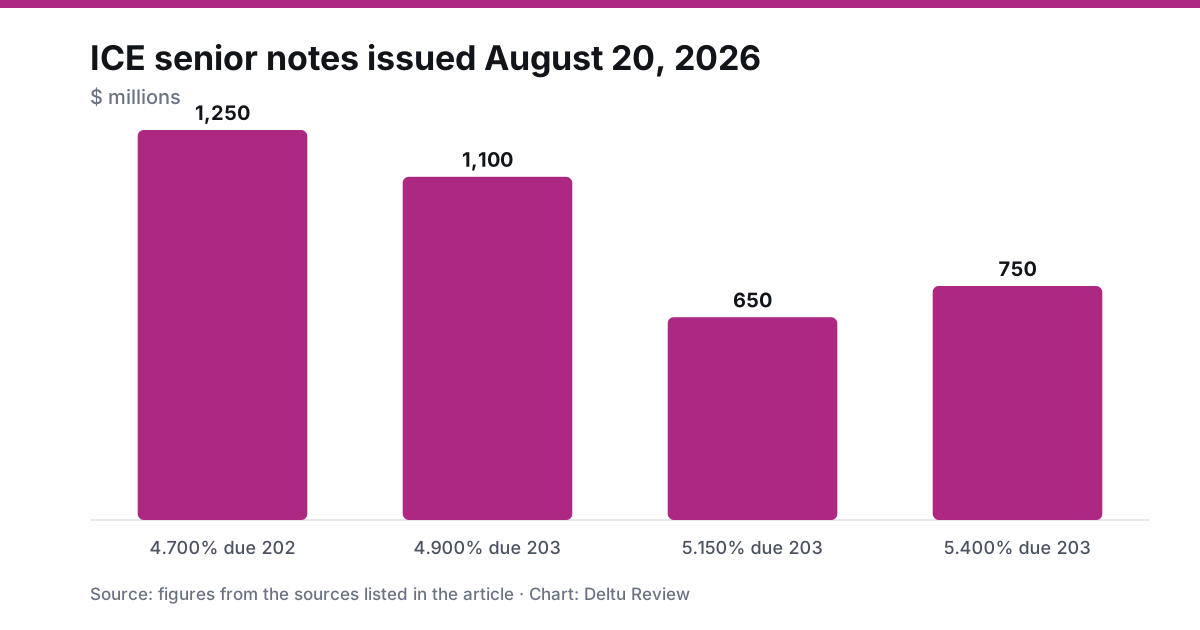
The consideration is paid entirely in cash, funded with new debt: bonds, a term loan and commercial paper. ICE also arranged a 364-day bridge facility of up to $6.25 billion with Bank of America as a backstop, and financing is not a condition to closing. Gross leverage is expected to start at 3.4 times, with a target of 3.0 times or lower within 18 to 24 months after closing. ICE raised its baseline buyback to $400 million per quarter from $350 million.
Deal protections and approvals
Closing requires adoption by a majority of MarketAxess shares and expiration of the Hart-Scott-Rodino waiting period, along with other regulatory approvals. ICE stockholders do not vote. The outside date is July 29, 2027, with up to two automatic six-month extensions if regulatory conditions remain open. MarketAxess owes ICE $148.8 million if it accepts a superior proposal or in other specified circumstances, and ICE owes MarketAxess $327.4 million if the deal is blocked under antitrust law or misses the outside date in specified regulatory circumstances. ICE is not required to accept structural or behavioral remedies. MarketAxess options, vested or unvested, and most restricted stock units convert into ICE awards.
What to watch
The antitrust review is the main variable, given the size of the regulatory fee. MarketAxess will file a proxy statement for its shareholder vote. ICE discussed the transaction on its second-quarter earnings call the same morning. For options traders, the news is indirect, but it shows how ICE is allocating capital outside derivatives.
Prepared with AI assistance from public sources and reviewed under our editorial policy. Not investment advice.